Sulfuric acid: cost support weakened yet demand keeps sluggish
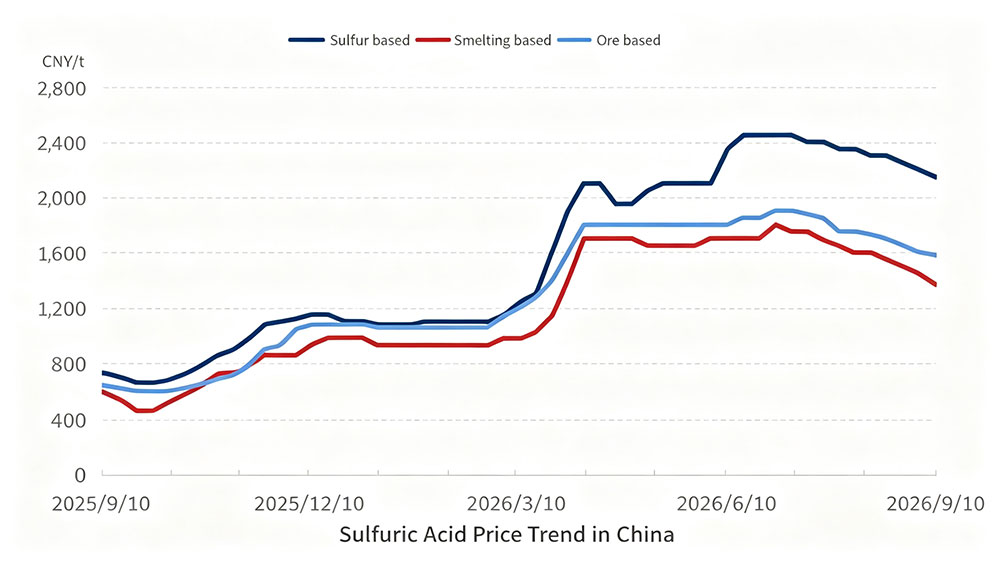
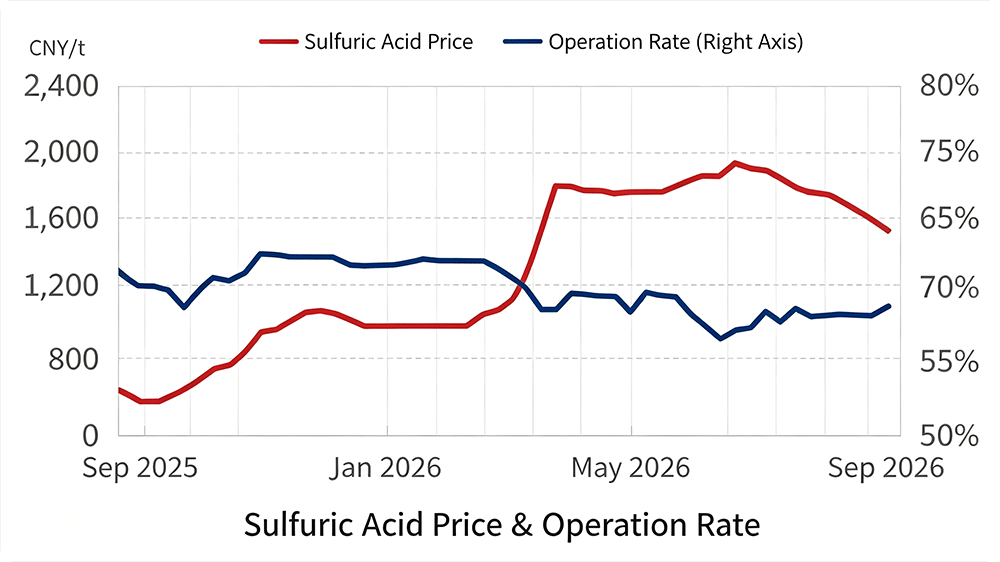
Sulfuric acid market has failed to meet the traditional “Golden September” peak season expectation this month. Intensified supply-demand conflicts drive price to keep falling. Until mid September, the price index of 98% sulfuric acid is quoted at CNY1,540/ton (-3.75% MoM). Although the price remains at a historically high level, the market sentiment has turned pessimistic due to weakened cost support, delayed downstream demand recovery and rising operating rate.
Supply side, the overall supply is abundant with negligible price support. In 1H of September, the domestic capacity utilization rate of sulfuric acid is 63.84% with a slight MoM increase. Units in Northwest, Shandong and North China resumed production, while only Hebei has production reduction from maintenance. Major acid plants in central Shandong has resumed production, pushing up the overall operation rate. Mainstream factories maintain stable production with sufficient supply and accumulated inventory. Suspended export divert export sources back to the domestic market, intensifying supply surplus. While planned maintenance facilities sharply canceled, keeps supply rising.
Demand Side, it shows structural differentiation with overall weak performance, failing to prop up the market. The fertilizers sector remains sluggish. MAP production operation rate drops significantly. DAP sees output growth but still limited. Compound fertilizer enterprises focus on inventory digestion and only purchase raw materials on rigid demand with strong price-cut willingness. The chemical sector recovers slightly with higher operation rate of titanium dioxide and caprolactam, yet widespread industry losses limit their capacity to bear high sulfuric acid prices. New energy demand is stable, yet it fails to offset the overall demand gap, leading to thin market transactions and strong wait-and-see sentiment.
Cost side, collapsed cost support further amplifies the downward pressure on acid prices. Sulfur price have fallen sharply from August highs with rising port inventories and lower international prices. Pyrite prices keep declining and the copper concentrate TC index remains deeply negative, eliminating the cost hedging effect for smelting enterprises. Currently, sulfur-based and ore-based acid production are in deficit, while smelting acid profits continue to shrink. The whole downstream industrial chain suffers losses, completely removing the cost bottom support for sulfuric acid price.
In short term, the market will remain weak and may keep bottoming before the National Day holiday. Logistics and transportation restrictions are approaching during the Mid-Autumn Day and National Day holidays, reducing products circulation efficiency. No large-scale production cuts or maintenance plans are arranged, keeping supply sufficient. The phosphate fertilizer and chemical industries can hardly boost overall demand. Downstream purchasing willingness will remain weak. Comprehensively affected by supply, demand, cost and market sentiment, the sulfuric acid market will fluctuate weakly with further downside price risks, cautious market atmosphere keeps on before the holidays.