P.A.: Market under pressure as supply increased under weak demand
Abstract: Phosphoric acid market remains sluggish with weak demand, both for hot-process and wet-process. Facilities operate at a medium-low rate. Buyers from new energy sector only place essential orders without incremental demand, leading to slow consumption. Some suppliers offer discounts for firm orders yet transaction volume hardly rises. Some factories also cut operation rate while new Hubei capacity ramps up to boost supply, keeping supply pressure high. Raw materials yellow phosphorus, phosphate rock and sulfur has no big change, weakening cost support. Weak demand plus expected supply expansion will keep the market under pressure in the short term.
I. New capacity release brings supply pressure
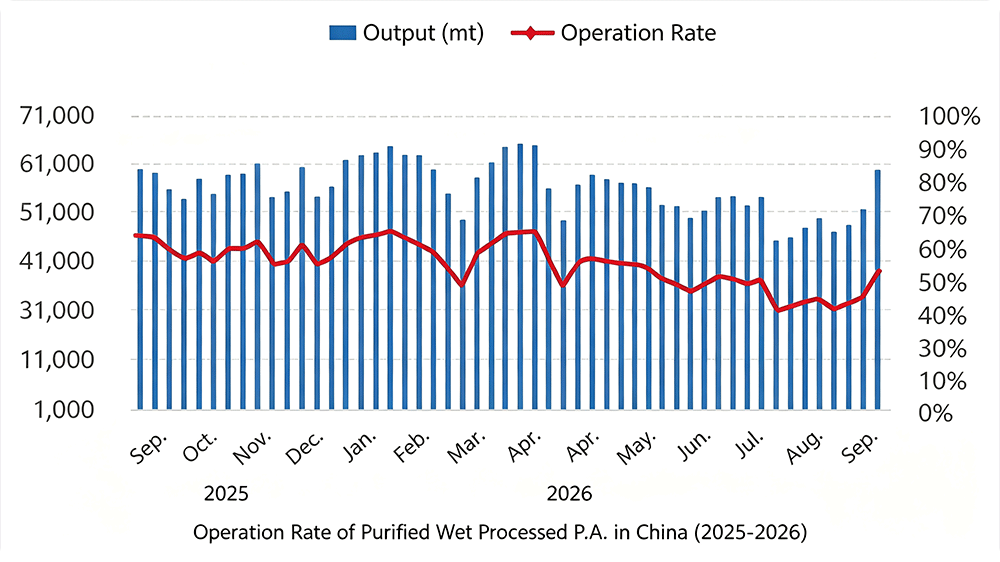
Total phosphoric acid output hits 89.9kt with an overall operating rate of 56.14%. Hot-processed P.A. output is around 30kt at 62.10% operation rate (-1.03% WoW). Wet-processed purified acid output reaches roughly 59.9kt at 53.56% operation rate (+7.57% WoW).
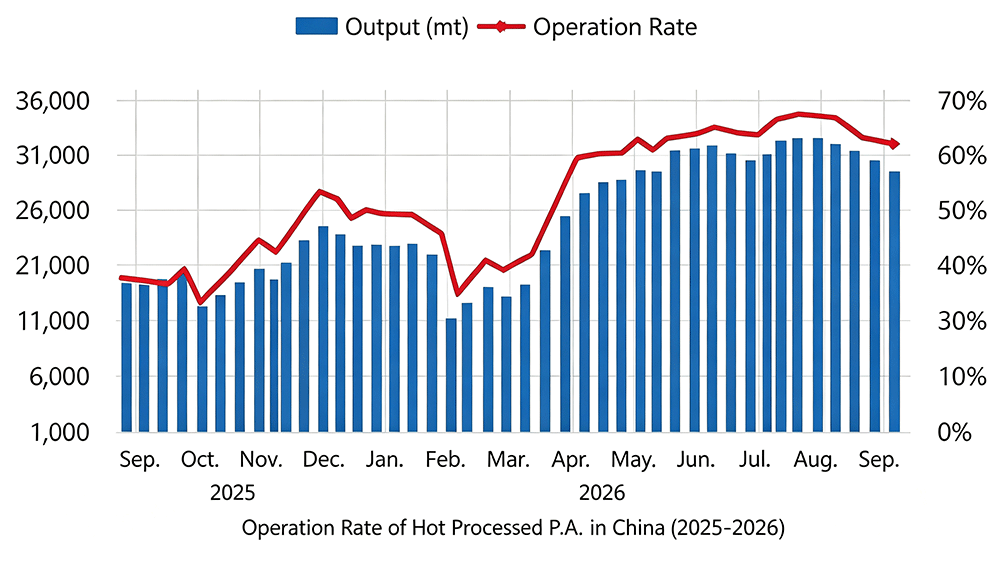
New wet-process purified P.A. units in Hubei keep ramping up and new hot-process facilities go into production. Previously maintenance / load-cut plants in Guizhou and Hubei resume operation, lifting market supply significantly. Demand is slow: traditional downstream sectors run at low rates with little support. The new energy sector maintains high operation rates but only purchases on an essential basis without extra demand. Rising supply fails to match demand growth, creating temporary oversupply and short-term market pressure.
II. International P.A. price sliding extend domestic pressure
For export market, purified phosphoric acid producers cut prices to stimulate demand. Food grade PPA is around USD1350-1400/t FOB. High domestic sulfur prices still underpin costs but cannot boost exports due to poor overseas buying interest and fierce competition. Some sellers hold back industrial grade PPA sales, and actual transactions remain difficult. Low price hot-processed PPA is competitive in Western Europe market, where buyers switch to small on-demand purchases. Rising energy and freight costs push up hot P.A. production cost, making low export prices unsustainable for long.
Weak exports force producers to expand domestic sales. Coupled with new Hubei capacity, domestic supply pressure intensifies. Suppressed by low international prices and sluggish domestic demand, the domestic phosphoric acid market will stay weak in the short term with little export support. In the medium and long run, continuously rising energy cost will erode the cost advantage of hot process and weaken export competitiveness, aggravating domestic production and sales pressure.