Sulfur: Ongoing Downtrend
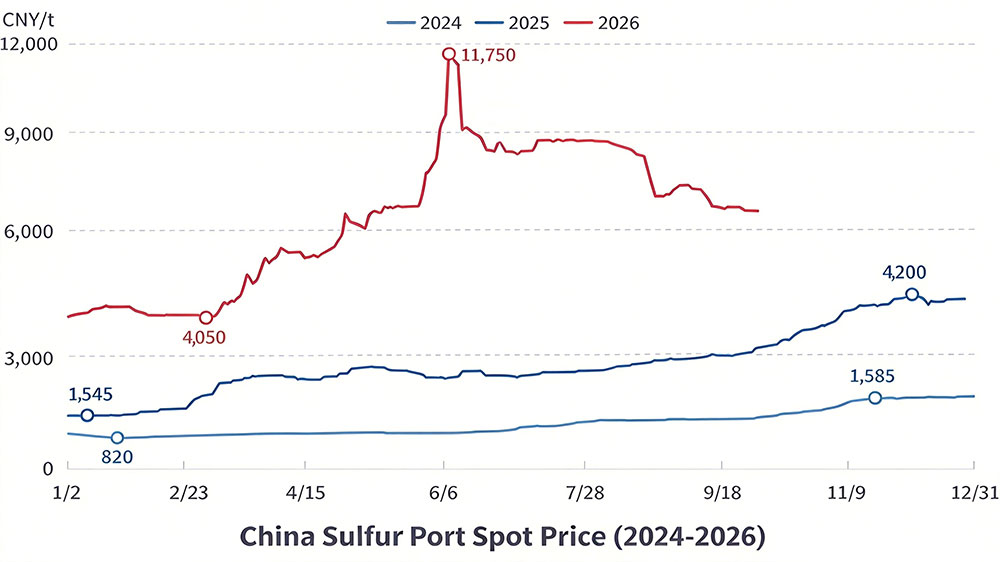
After the National Day holiday, China’s sulfur spot market failed to rebound. Import volume compensation is limited so traders still hold their offer, yet sluggish demand and still high prices led to slow trading actions with few purchases. The previous strong international sulfur market slumped. Domestic sulfur has not followed the downtrend, while upward momentum vanished and downside risks are building up.
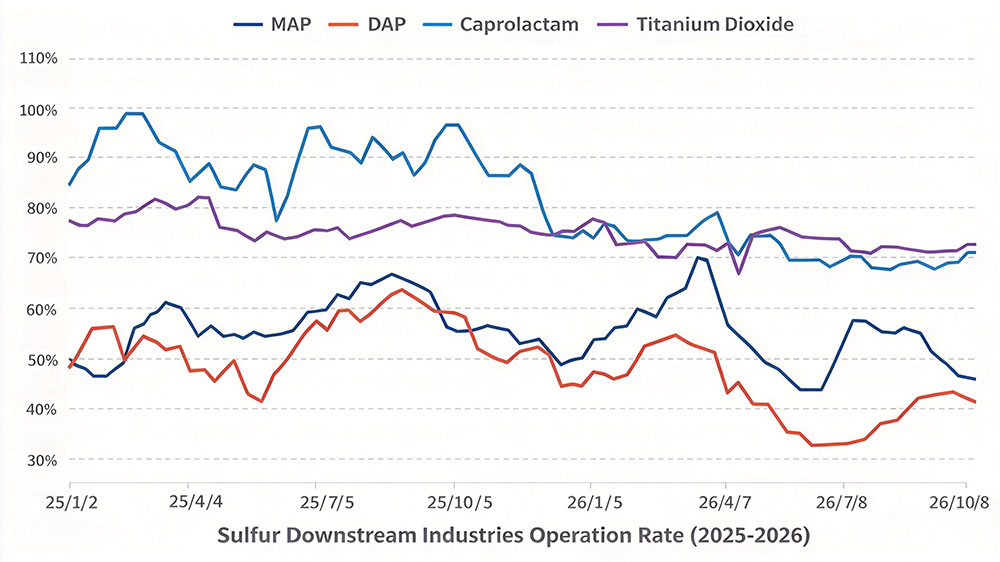
Domestic sulfur demand is mainly driven by phosphate fertilizer production. The major state owned groups continue targeted supply guarantee to stabilize raw materials supply for phosphate producers. So the willingness is not strong for further replenishment. Export of phosphate fertilizers and sulfuric acid is still restricted. Although the autumn fertilizer season is starting, weak end user demand, falling cost and sufficient supply dragged down phosphate fertilizer market with chaotic quotations and abundant low-priced cargo. Slow inventory digestion and medium-low operation rate limited rigid demand for sulfur. Sulfur stays at a relatively high level. Except long term contract buyers, most traders stick to wait & see mood. The market lacks of sustained purchasing support. Spot buyers remain scarce with thin trading activity.
Different from September, international sulfur turned weak recently. October official prices from the Middle East were released: Qatar, UAE and Kuwait contract FOB prices stood at USD835/t, USD890/t and USD820/t respectively (about USD45-70/t decrease MoM). The contract price cuts were within expectation, while declining CIF prices in other markets surprised industry participants, as some traders misjudged the strong overseas market previously. International spot prices were further lower recently, offers for Indonesian inquiries dropped to USD875-900/t CFR. Multiple vessels carrying Middle East sulfur passed through the Strait of Hormuz, easing supply concerns and further dampening market sentiment.
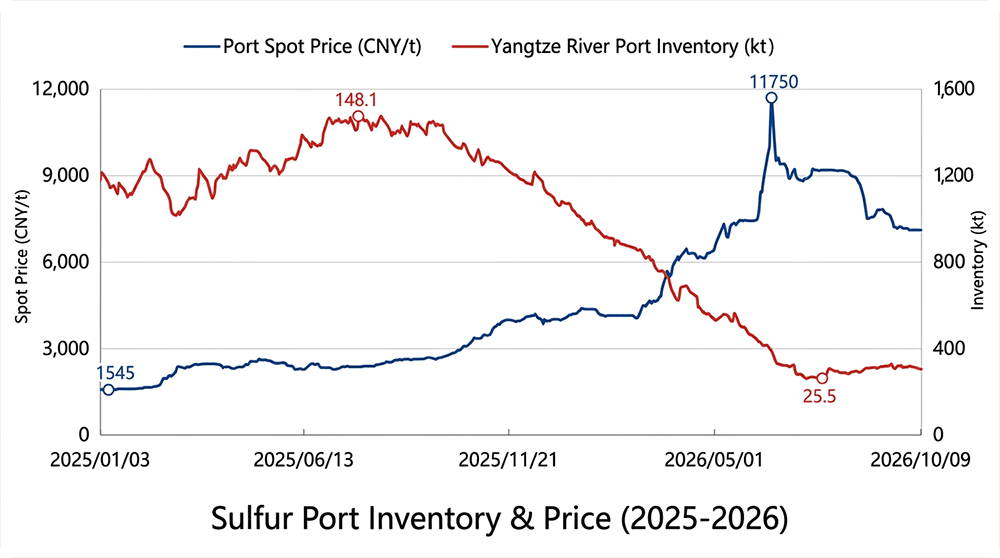
No positive signals appear on supply and demand fundamentals for the outlook. Domestic sulfur output remains stable and targeted supply guarantee continues from the state owned companies. Import arrivals are constrained by high-price risks. Restrictions on phosphates and sulfuric acid exports will not be lifted in the short term, leaving little room for increased end-user rigid demand. Continuous monitoring is required to check whether Middle East sulfur cargoes would enter Chinese market, after passing the Strait of Hormuz during the holidays.
Market sentiment stays negative. Holders intend to defend prices, yet weak demand outlook will test how long they can sustain such strategy. Faced with high-price risks, most traders adopt a market-following stance and delay purchases before price trends clarified, amplifying wait & see sentiment.
In summary, China’s sulfur market is in a sensitive phase of high price stalemate with hidden changes. Restrained demand and falling international prices may worsen supply-demand imbalance. Supported by long-term contracts, the market can maintain superficial stability in the short run. However, after the long term contract replenishment finished, bargaining power will shift to buyers. Domestic spot prices are expected to come down. Market players are advised to track market sentiment, sales & tender updates and vessel arrival schedules, adjust operations timely and avoid downside price risks.