Yellow Phopshorus: market was stable-to-firmer. The benchmark held at CNY 27,766/t, WoW flat (-0.5% MoM). Post-holiday mainstream acceptance prices stood at CNY 27,800/t in Yunnan/Sichuan and CNY 28,000/t in Guizhou, with suppliers tentatively lifting offers on thin watchful demand and decent follow-on orders. Falling electric-power and sulfur costs cap the upside for the thermal processed materials.
Phosphoric Acid: generally stable. Thermal/industrial grade quoted at CNY 8,375/t, WoW flat (−0.89% MoM). Wet-process grade quoted at around CNY 7,967/t. With autumn phosphate fertilizers season wrapping up, downstream buying was slow down, P.A. prices follow the weakening yellow phosphorus cost with no clear direction.
Sulfur: keeps downtrend. Domestic benchmark fell from CNY 7,686/t at month-start to CNY 7,392/t, down 4.02% WoW (over -10% MoM). Overseas softened: CFR China granular sulfur at USD 960-970/t. Qatar’s October contract price closed at USD 835/t FOB (-$45/t). Solid sulfur in North China dropped to CNY 7,080-7,210/t, with port prices tracking lower on hand-to-mouth buying.
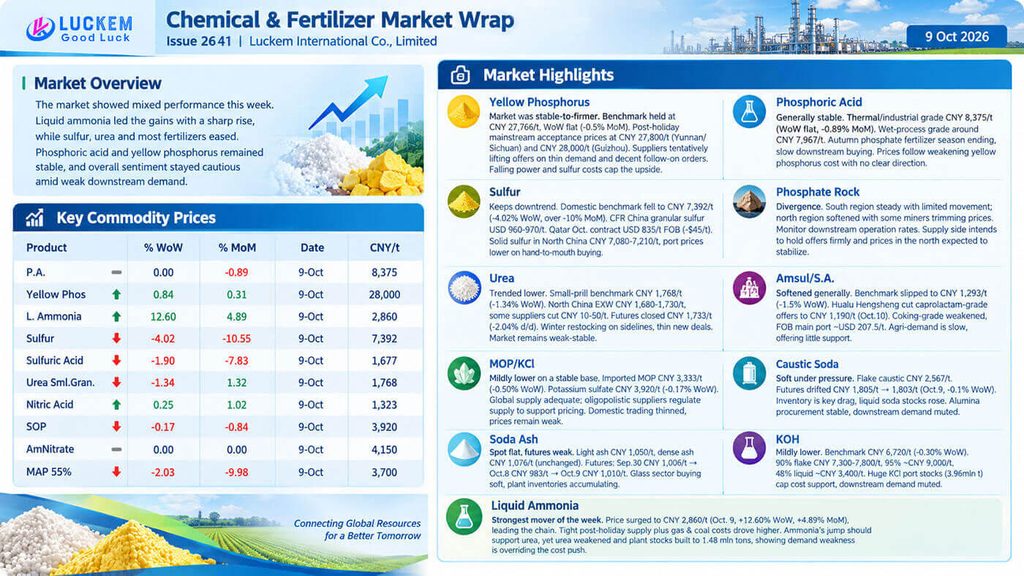
Phosphate Rock: market divergence. In China south region, phosphate rock held steady with limited movement. While in the north region, market softened with a few miners trimming prices before and after the holidays. Downstream operation rates should be monitored, supply side intends to hold the offer firmly and prices in the north is expected to be stabilized.
Urea: trended lower. Small-prill benchmark at CNY 1,768/t, down 1.34% WoW. Mainstream EXW price in North China was CNY 1,680-1,730/t, some suppliers cuts CNY 10-50/t. Urea futures closed at CNY 1,733/t on Oct. 9, down 2.04% in a day. Winter restocking stayed on the sidelines with thin new deals. Market would remain weak-stable situation.
Amsul/S.A.: softened generally. Benchmark slipped from CNY 1,313/t (Oct. 6) to CNY 1,293/t (Oct. 9), roughly down 1.5% WoW. Major producer Hualu Hengsheng cut caprolactam-grade offers to CNY 1,190/t on Oct. 10. Coking-grade also weakened, with FOB main port at around USD 207.5/t. Agri-demand is slow, offering little support.
MOP/KCl: mildly lower on a stable base. Imported MOP benchmark at CNY 3,333/t, slide 0.50% WoW. Potassium sulfate at CNY 3,920/t (-0.17% WoW). Global market supply has no absolute deficit and oligopolistic suppliers regulate the market supply to support pricing. Domestic trading thinned at the tail of autumn fertilizers season, prices would remain weakened.
Caustic Soda: soft under pressure. Flake caustic benchmark held at CNY 2,567/t. Futures price drifted from CNY 1,805/t to CNY 1,803/t (Oct. 9, -0.1% WoW). The key drag is inventory, liquid soda stocks rose. Alumina procurement was stable, but downstream demand is muted.
Soda Ash: spot flat, futures weak. Light soda ash reference price was CNY 1,050/t and dense ash was CNY 1,076/t, both unchanged from early October. Futures price fluctuated: Sep. 30 closed CNY 1,006/t → Oct. 8 crash to CNY 983/t → Oct. 9 rebound to CNY 1,010/t. Downstream glass sector buying is soft and ash plant inventories are accumulating.
KOH: mildly lower. Benchmark slipped from CNY 6,740/t (Oct. 1) to CNY 6,720/t (Oct. 9, -0.30% WoW). 90% flake EXW quoted CNY 7,300-7,800/t, 95% around CNY 9,000/t, 48% liquid KOH around CNY 3,400/t. Huge KCl port stocks (about 3.96mln tons) cap cost support, downstream demand is muted, leaving prices in a soft narrow range.
Liquid Ammonia: strongest mover of the week. Price surged to CNY 2,860/t (Oct. 9, +12.60% WoW and +4.89% MoM), leading the entire chemicals chain. Tight post-holiday supply plus cost push from gas & coal drove ammonia higher. Divergence notice: ammonia’s jump should support urea, yet urea weakened and plant stocks built to 1.48 mln tons. It reflects that demand weakness is overriding the cost push.