TMAP Trends Down as Raw Materials Cost Slides
Abstract
Since September, domestic sulfur prices have kept falling, dampening market sentiment. Sulfuric acid has also weakened, eroding cost support and easing production pressure for manufacturers. Phosphate fertilizer market is in slack season with winter reserves not yet launched, leading to a sluggish demand and limited trade. Stable new-energy demand forms floor support, yet buyers are cautious on high-price TMAP with actual negotiations. Price trough keeps going down, avg. price is CNY6,600-6,900/t EXW. Downstream restocking will be finished before the holidays(Mid-Autumn Day + National Day), so producers are reluctant for sharp price drops in short term.
Sulfur falls from high level with weak outlook
Middle-East geopolitical risks premium fades. Port arrivals plus rising refinery by-product sulfur improve market supply. Downstream phosphate fertilizer plants operate at low rates amid cost inversion, purchasing only for immediate consumption without active restocking. Autumn fertilizer demand fades, weighing on spot prices. Sulfur will stay weak-oscillating with minor downside; import costs set floor to prevent steep slump.
Divergent trends for phosphate rock, synthetic ammonia and sulfuric acid
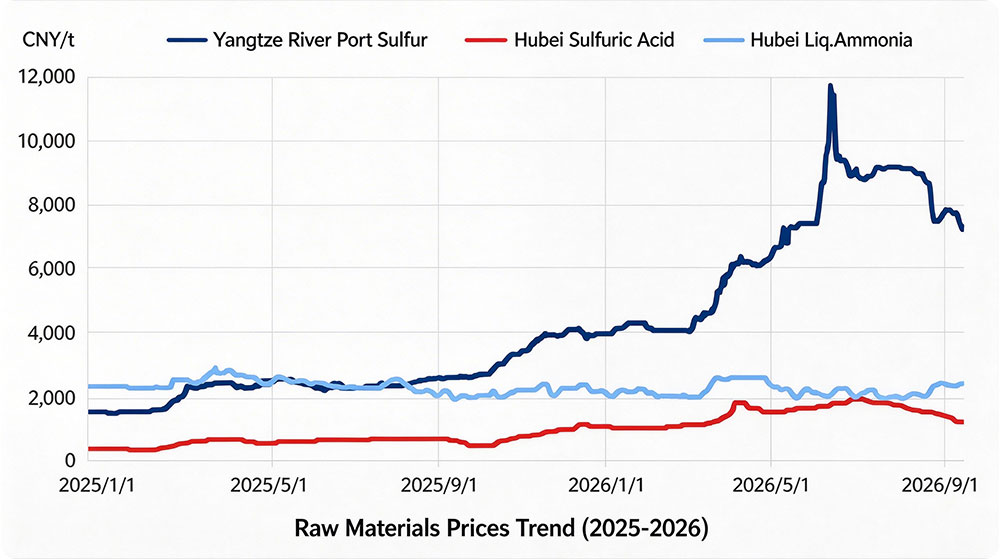
Phosphate rock hovers narrowly at high stage with firm high-grade offers and steady mine supply. While phosphate fertilizer production operation rate is low with only rigid demand, lacking upward momentum. Long-term tight resource balance persists. Synthetic (liquid) ammonia rallies as facilities in the north start maintenance and output cuts, price hits new H2 high. However, weak downstream acceptance for high prices resists market uptrend. Sulfuric acid stays weak, sulfur-based and smelting based acid output rises and inventory is accumulated. Compound fertilizers and chemical sectors resist high prices, pushing transaction prices lower with widening regional gaps. Market is unlikely to recover in short term.
Winter fertilizer reserves pending
Sluggish agricultural market weighs on TMAP. Demand is poor as water-soluble fertilizer market enters slack season. Fertilizer end users hold leftover stocks and buy only minimal limited volumes for rigid demand. Traders stay on sidelines, widening bargaining range and depressing deals for agri. market.
New–energy sector underpins market
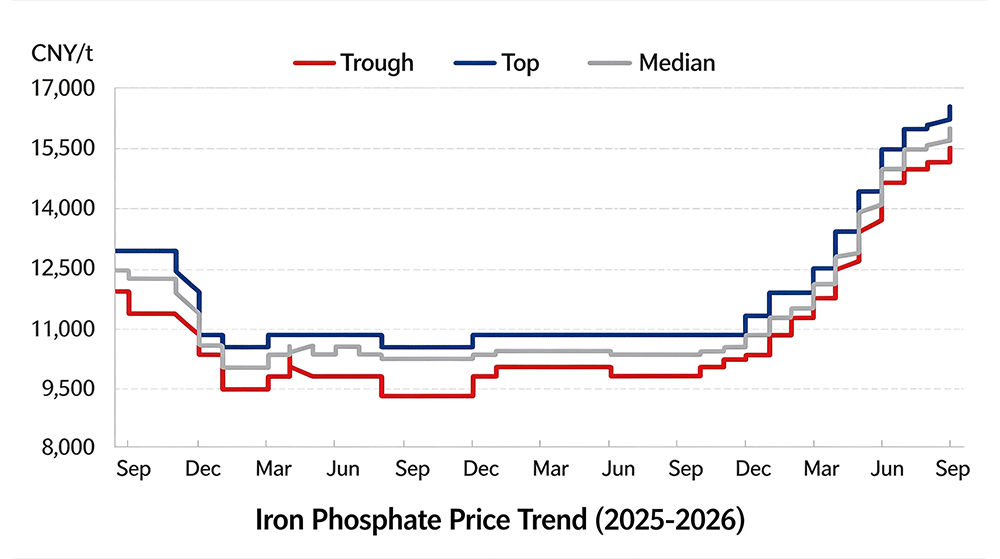
New-energy demand offers solid support to TMAP market. The leading iron-phosphate producers secure supply via long-term contracts with priority allocation. Strict purity requirements on TMAP push new-energy grade deals at least CNY300-500/t higher than the TMAP for agricultural use. However, new orders in September is limited, TMAP-based LFP can not lift the prices but it can cap price downtrend, resulting a structural market divergence.